Transfer Pricing in India: A Strategic Guide for Global Companies

Expanding into India? Operating an Indian subsidiary? Managing cross-border transactions with your global group?
For global companies, India can be an important market, manufacturing hub, technology centre and service-delivery location. But operating across jurisdictions also brings a critical question: How should transactions between the Indian entity and its overseas group companies be priced, documented and managed?
Whether your group is charging India for technology, management or support services, supplying goods to an Indian subsidiary, receiving services from India, licensing intellectual property, extending intercompany financing or operating an Indian distribution or manufacturing model, transfer pricing can significantly influence your global tax position and the level of tax risk within the group.
India has a comprehensive transfer pricing framework based on the Arm’s Length Principle. Global companies therefore need to ensure that their Indian intercompany transactions are not only commercially appropriate, but also supported by robust economic analysis, appropriate benchmarking and contemporaneous documentation.
For multinational groups, the challenge is often greater than simply complying with Indian rules. The Indian transfer pricing position needs to work alongside the group’s global transfer pricing policy, international tax strategy, operating model and requirements in other jurisdictions.
This guide provides a practical overview of Transfer Pricing in India for global companies, covering the arm’s length principle, FAR analysis, benchmarking, intercompany transactions, documentation, compliance and key considerations for multinational groups.
Why Global Companies Need to Pay Attention to Indian Transfer Pricing
When a multinational group establishes or expands its Indian operations, the structure of intercompany transactions can have a direct impact on where profits are recognised and how those profits are taxed.
Common arrangements include:
- Overseas parent companies providing services to India
- Indian subsidiaries providing services to overseas group companies
- Cross-border purchase and sale of goods
- Contract manufacturing arrangements
- Distribution and marketing arrangements
- Technology and intellectual property licensing
- Management and administrative services
- Intercompany loans and financial guarantees
- Cost-sharing and shared-service arrangements
Each arrangement can raise different transfer pricing considerations.
A transfer pricing policy designed at the global level should therefore be carefully evaluated before it is applied to the Indian business.
The India–Global Alignment Challenge
One of the most important considerations for multinational groups is ensuring consistency between global transfer pricing policies and Indian requirements.
A global policy may establish a particular operating model or target margin for an entity. However, the Indian analysis must still reflect the actual functions performed, assets employed and risks assumed by the Indian entity.
This is where a detailed Functions, Assets and Risks (FAR) analysis, appropriate benchmarking and transaction-specific assessment become important.
A strong approach seeks to balance:
Global consistency + Indian regulatory requirements + Commercial substance
That balance can help multinational groups build a more defensible and sustainable transfer pricing framework.
A Strategic Approach for Global Businesses
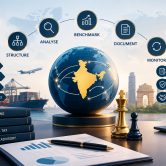
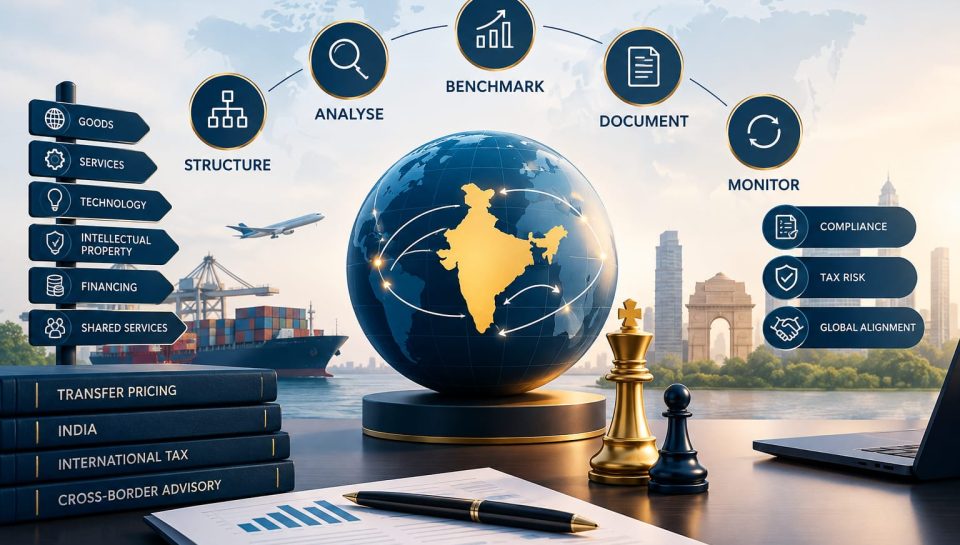
Global companies entering or operating in India should consider transfer pricing at the business-structuring stage, rather than treating it solely as an annual compliance exercise.
Before implementing an intercompany arrangement, businesses should consider:
1. Structure
Understand how the Indian entity fits within the global operating model.
2. Analyse
Identify the functions, assets and risks of each participating entity.
3. Benchmark
Determine an appropriate arm’s length outcome using reliable economic analysis.
4. Document
Maintain clear support for the pricing methodology and commercial rationale.
5. Monitor
Review the arrangement when the business model, functions, risks or market conditions change.
How Expanzia Global Can Help Global Companies
At Expanzia Global, our focus is on helping international businesses navigate the Indian side of their cross-border tax and transfer pricing requirements.
We can support global companies with:
- India transfer pricing advisory
- Intercompany transaction review
- FAR analysis
- Economic benchmarking
- Transfer pricing documentation
- Intercompany service arrangements
- Royalty and intellectual property transactions
- Intercompany financing analysis
- Manufacturing and distribution models
- India–global transfer pricing alignment
- Transfer pricing compliance and tax-risk management
Our approach is designed to connect Indian regulatory requirements with the commercial and international tax objectives of the global group.
India Is an Opportunity. Transfer Pricing Should Not Become an Unexpected Risk.
For global companies, getting the Indian transfer pricing framework right from the beginning can provide greater transparency, consistency and tax certainty.
Whether your group is entering India, restructuring its Indian operations, reviewing existing intercompany arrangements or preparing for transfer pricing compliance, Expanzia Global can help you develop a practical and commercially aligned approach.
Expanzia Global — Supporting Global Businesses with India-Focused Transfer Pricing, International Tax and Cross-Border Advisory.